What constitutes a valid schedule of trust assets is a clear, specific record connecting identifiable property to the trust, but a schedule alone does not change legal title. If a California home appears on the schedule while the deed names the trust creator individually, that mismatch needs careful review.
Compare each schedule entry with the trust document and the relevant ownership records. Heggstad Help, a service of attorney Robert P. Bergman, Board-Certified Specialist in Estate Planning, Trust, and Probate Law (California State Bar Board of Legal Specialization), assists families, attorneys, title companies, and their clients throughout the State of California with uncontested ex parte Heggstad petitions in Santa Clara County, regardless of where the trust is located.
Key Takeaways
- What constitutes a valid schedule of trust assets depends on how clearly it identifies property and how it relates to the trust, not on a particular layout alone.
- Compare each listed asset with ownership records, such as a deed or account record, and flag mismatched names or descriptions.
- Organize the trust document and schedule, group assets by type, and separate clearly identified trust assets from assets with uncertain ownership.
- If an asset is listed but titled outside the trust, a Heggstad petition may ask a California court to confirm trust ownership.
What Constitutes a Valid Schedule of Trust Assets?
A schedule is most useful when its entries can be matched to specific property and read alongside the trust document and ownership records. There is no single layout that proves every listed asset belongs to the trust, so use the schedule as part of a document review, not as a replacement for title or account records.
What Is a Schedule of Trust Assets, and What Does It Establish?
A schedule of trust assets is an inventory identifying property associated with a trust. Its significance depends on how the trust instrument, the document that sets out the trust, refers to the schedule and how the listed assets match their ownership records.
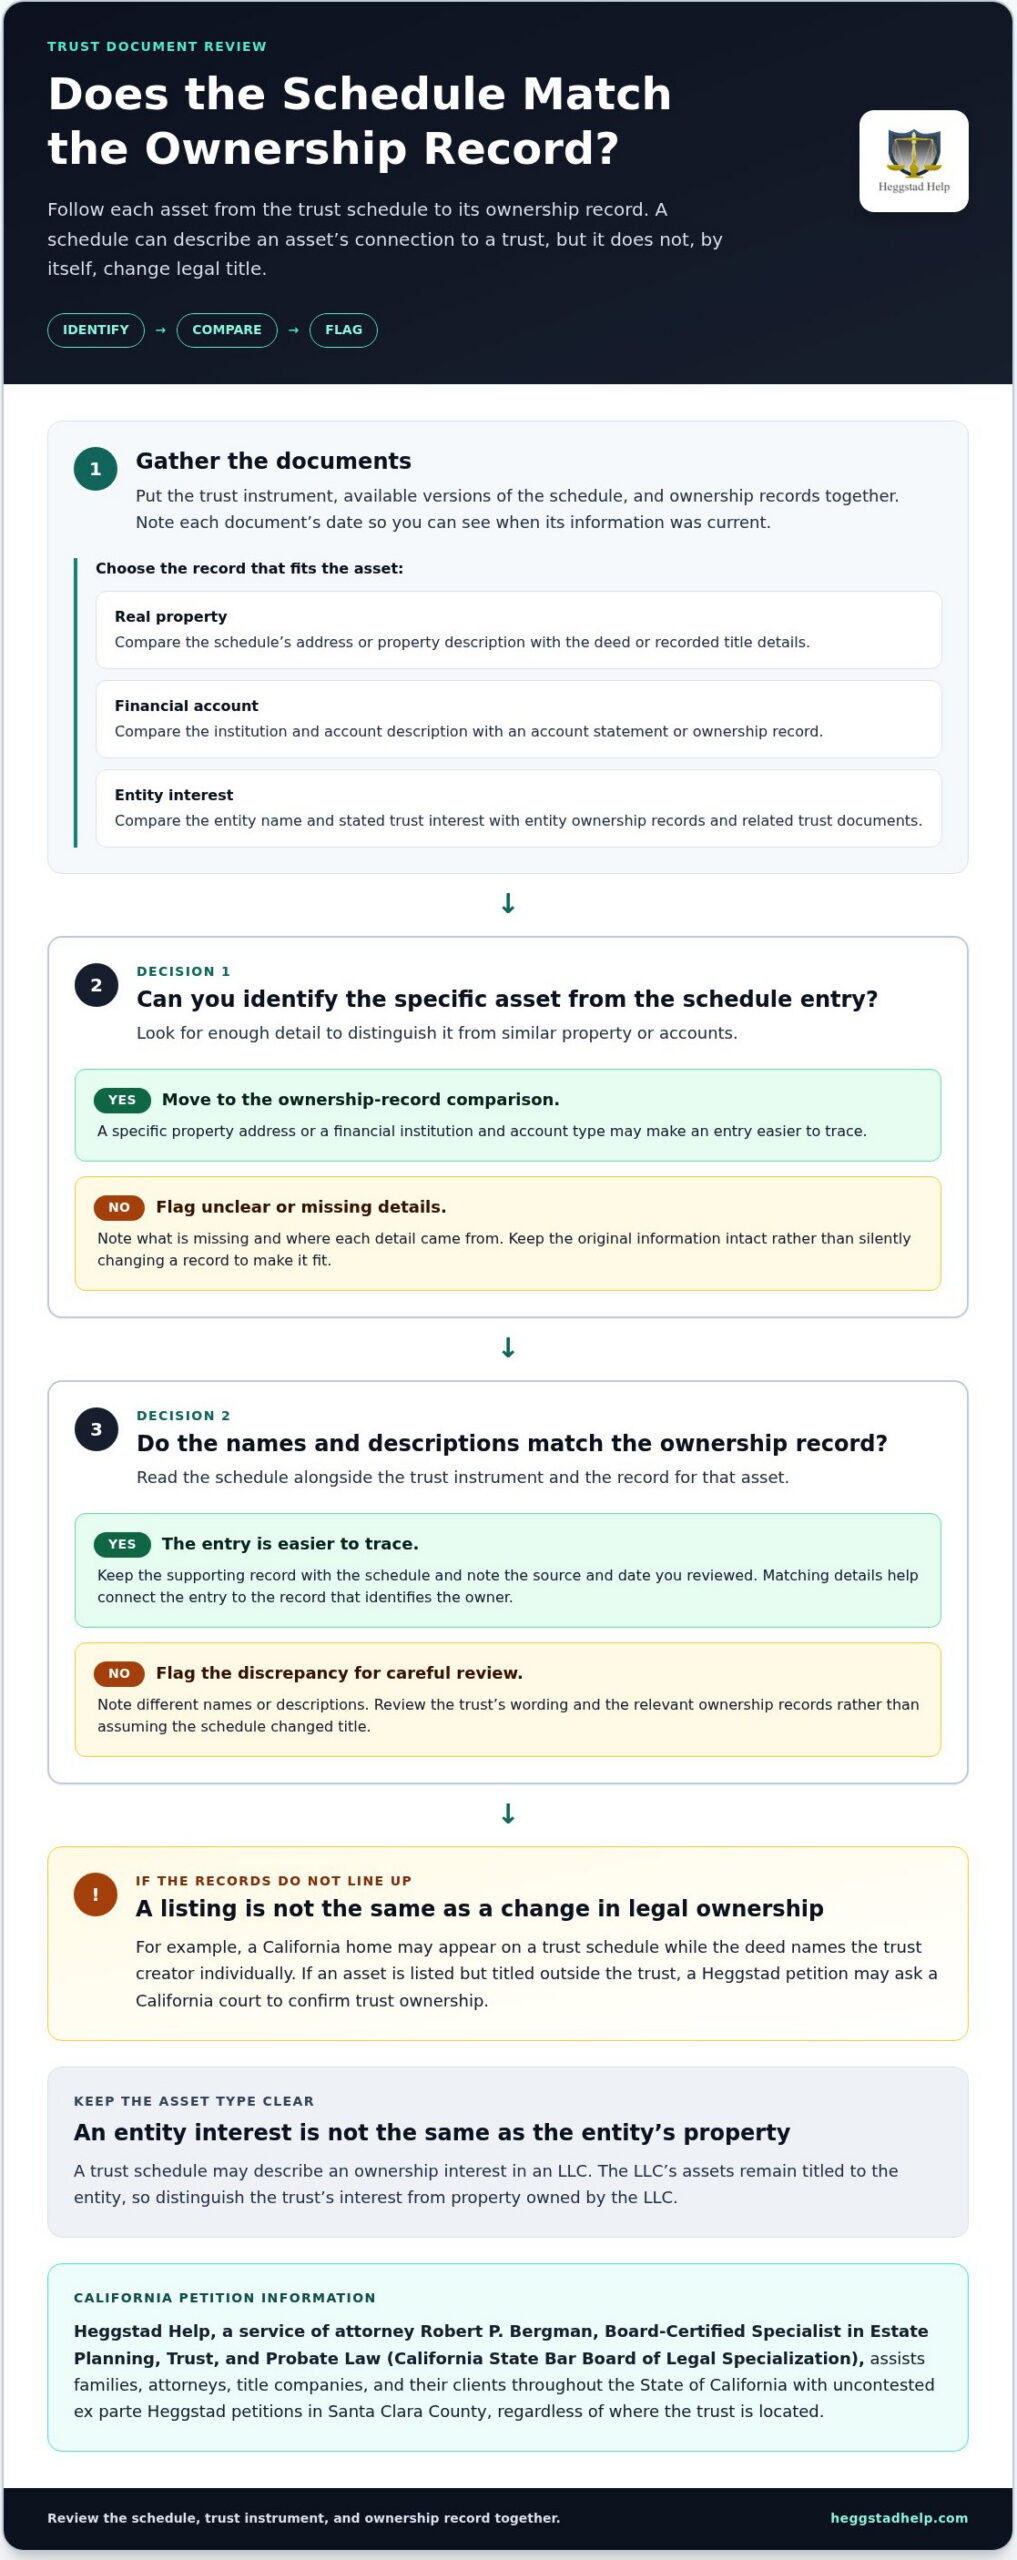
Listing an asset on a schedule describes its connection to the trust; it does not, by itself, document or change legal ownership. Treat the schedule as one piece of information to review, not as a substitute for a deed, account record, or other ownership documentation.
Is a schedule the same as a deed or account record?
No. A schedule groups or describes assets, while a deed or account record identifies ownership in a different way. For example, a California home might appear on a trust schedule by address, while the deed names an individual as the owner. The listing does not automatically change the recorded title. Compare the schedule with the deed and the trust’s terms, and note any differences in names or property details.
Why can the document’s role vary?
A schedule’s significance depends on its wording and context, including how the trust instrument refers to it, the type of asset, and the relevant ownership records. Trusts involve roles such as a settlor, the person who creates the trust, a trustee, the person who manages it, and beneficiaries, those intended to benefit. The general overview of Trust (law) explains these terms.
Read the schedule alongside the trust instrument and records for each asset rather than relying on the list alone. Gather the documents and compare the asset descriptions and owner information. This helps distinguish a clear inventory entry from a question about whether title or account ownership was actually placed in the trust.
What Details Make a Schedule of Trust Assets Clear and Useful?
A useful schedule describes assets clearly enough that a successor trustee can tell which property each entry refers to. What constitutes a valid schedule of trust assets depends on the trust’s language and the records for each asset, so treat the examples below as practical clarity tips, not required fields.
| Asset category | Helpful identifying details | Record to review |
|---|---|---|
| Real property | Property address and a description that distinguishes it from other real estate | Deed or recorded title details |
| Financial account | Financial institution, account type, and enough identifying information to distinguish the account | Account statement or ownership record |
| Entity interest | Entity name and the interest described as owned by the trust | Entity ownership records and related trust documents |
How specific should an asset description be?
Use wording that helps a reader distinguish the asset from similar property. For example, “residence” may be less useful than a California property address; “investment account” may be less clear than the institution and account type. These examples improve clarity but are not a checklist of legal requirements.
What records should be compared with the schedule?
Review the trust instrument alongside deeds, account statements, and entity ownership records. Compare names and descriptions across documents, and note differences instead of assuming they match. Matching names and descriptions makes it easier to trace each schedule entry to the record that identifies the asset’s owner.
An LLC interest is distinct from property owned by the LLC. The trust schedule may describe an ownership interest in the entity, while the LLC’s assets remain titled to the entity. The related article Transferring an LLC to Trust After Death: The Heggstad Solution explores this distinction. If an asset’s title needs correction or court confirmation, trust asset title correction may be a relevant next step.
How Can You Prepare and Review a Trust Asset Schedule?
A consistent review helps a successor trustee see what each entry refers to and where the supporting information comes from. Use these four steps to organize the documents and identify questions without changing ownership details.
- Gather the trust and schedule. Put the trust instrument, every available version of the schedule, and related ownership records together. Note each document’s date so you can tell which information was current when it was prepared.
- Group the assets. Sort entries into useful categories, such as real property, financial accounts, and entity interests. Keep assets that appear trust-related separate from those titled to someone else or whose ownership is unclear.
- Compare the records. Check each entry against the trust instrument and available deeds, account statements, or entity ownership documents. The records can help show whether the schedule’s wording and the ownership information refer to the same asset.
- Flag discrepancies. Mark missing details, different names, or descriptions that do not clearly match. Keep the original information intact rather than silently changing a record to make it fit.
What should a successor trustee check first?
Start with the schedule’s date and wording, then compare them with the trust instrument and available ownership documents. Record the source of each detail, such as a particular statement or deed, and the date you reviewed it. This gives later reviewers context and makes it easier to follow up on uncertain entries.
How should unclear or changing assets be handled?
Balances and account holdings can change, so note when the schedule or your review was prepared. If an entry is unclear, mark it for follow-up instead of assuming it establishes ownership. Also distinguish an interest in an LLC from property titled to the LLC itself. If the documents leave a question about whether an asset belongs to the trust, court confirmation may be needed. A California Probate Code Section 850 petition is one possible process to address it.
If an asset’s title needs review or correction, explore trust asset title assistance.
What If an Asset Is Listed but Its Title Is Outside the Trust?
A schedule entry can help show that an asset was intended to be part of a trust, but it does not, by itself, resolve a mismatch in recorded or account ownership. If the trust instrument and related records support the request, a Heggstad petition may ask a California probate court to confirm that an asset belongs to the trust even though title was not formally transferred. The court decides whether the evidence supports that result.
Before considering that step, gather the trust instrument, schedule, and ownership records, then identify exactly where the names or descriptions differ. This gives the petition a clearer factual foundation and helps distinguish a title issue from an asset that may belong to someone else.
Where may a California Heggstad petition be filed?
For an uncontested matter, a petition involving a trust located outside Santa Clara County may be filed ex parte in Santa Clara County, meaning without a formal hearing. In other counties, Heggstad petitions often require a noticed hearing, where interested parties receive notice, and may take many months to be heard. Santa Clara County petitions are typically granted in 7 to 10 days after filing, but no court outcome is guaranteed. For broader context, see Heggstad Petition Filing: The California Guide to Recovering Missing Trust Assets in 2026.
Heggstad Help assists families, attorneys, title companies, and their clients throughout the State of California, including the San Francisco Bay Area, Northern California, Southern California, the Central Valley, San Diego, Sacramento, Fresno, Bakersfield, Greater Los Angeles, Orange County, Riverside County, and San Bernardino County. The practice serves clients with trusts and property in counties including Santa Clara, San Mateo, Contra Costa, Los Angeles, Alameda, San Francisco, Marin, San Diego, Orange, Riverside, Sacramento, Fresno, Ventura, Santa Cruz, Placer, Santa Barbara, San Joaquin, Solano, San Luis Obispo, and Monterey.
How can specialized help make the next step clearer?
Heggstad Help assists families, attorneys, title companies, and their clients throughout the State of California with uncontested ex parte Heggstad petitions. Petitions may be filed in Santa Clara County, San Mateo County, or Contra Costa County. Santa Clara County petitions are typically granted in 7 to 10 days; San Mateo County petitions can be filed, heard, and granted the same day. In Contra Costa County, same-day filing and approval may be possible when the Court is satisfied that urgency has been demonstrated. Fixed fees cover filing fees and attorney fees. For a California title issue, explore uncontested Heggstad petition services.
Turn a Title Question Into a Clear Next Step
A difference between a trust schedule and an ownership record does not have to leave your family guessing. Keep the relevant records together, identify exactly what does not match, and avoid changing ownership details based on the schedule alone. This helps clarify whether the issue is incomplete information or whether the trust’s ownership of an asset needs court confirmation.
Understanding what constitutes a valid schedule of trust assets is useful, but each situation depends on the trust document and the records tied to the asset. If those documents leave a California trust-title issue unresolved, a focused review can help identify a practical path forward.
Explore uncontested Heggstad petition help for guidance on a California title issue. With the relevant records in hand, you can take the next step with greater clarity.
Frequently Asked Questions
Is a schedule of trust assets legally binding?
There is not one answer for every schedule. To understand a particular document’s role, check whether the trust refers to it and whether later trust documents or schedule versions exist. Make a simple timeline of the dates shown on those records, and keep the versions together. This can clarify which documents were in place when the trust creator made decisions about an asset.
Does listing a house on a trust schedule put it into the trust?
No, the schedule entry alone does not establish that the house was transferred into the trust. For a practical review, locate the deed’s legal description, which identifies the property more precisely than a street address, and compare it with the schedule and trust paperwork. Keep the documents unchanged and note any differences for California-specific legal review before drawing conclusions about ownership.
What should a schedule of trust assets include?
Include enough identifying information to distinguish each asset from similar items, with details suited to the asset type. For example, a collection of valuable personal property may need individual descriptions rather than a broad label such as “household items.” As a privacy precaution, avoid placing full account numbers on copies that do not need them; retain relevant records securely for authorized review.
Can an asset be on a trust schedule if an LLC owns it?
A schedule can refer to an ownership interest in an LLC, but do not describe the LLC’s property as though the trust directly owns it. To clarify the records, look for documents that identify the LLC’s members and their interests, such as an operating agreement or membership ledger, if available. Compare those details with the trust paperwork before describing the interest in an inventory.
What can California families do if an asset is listed but titled outside the trust?
Preserve the documents and make a short chronology of relevant events, such as when the trust and schedule were prepared, when the asset was acquired, and whether title-transfer steps were attempted. This can help organize the facts for evaluating a possible Heggstad petition. Heggstad Help handles uncontested petitions; whether a petition is appropriate depends on the trust documents and the evidence for that asset.

Article by
Robert P. Bergman, Attorney at Law
Attorney Robert P. Bergman ("Bob Bergman") has been a Board-Certified Specialist in Estate Planning, Trust and Probate Law since 2011, as certified by the California State Bar Board of Legal Specialization. For several years, Bob has assisted families and the clients of other attorneys with obtaining court orders through Heggstad petitions to avoid the time and expense of Probate administration. Bob is friendly, very approachable, and believes in explaining complex legal topics in clear ordinary language so that his clients understand exactly what they're doing and why they're doing it.
Bob is often able to assist clients who are in other counties than his home county of Santa Clara through his approach to Heggstad petitions.
Disclaimer
This article is for informational purposes only. Nothing in this article is intended to replace legal advice from a competent attorney or be considered legal guidance for anybody's specific legal situation. Nobody should rely on information in this article in making legal decisions without such consultation.